Latest by
-
 Rising Treatment Duration and Insurance Costs for Accident Victims A man diagnosed with back and knee sprains following a traffic accident in March 2024 has undergone over two years of outpatient treatment at a traditional medicine clinic. He has visited the clinic 141 times and received 57 medical certificates, 34 of which were issued without any additional examination.As the implementation of the so-called '8-week rule' to manage the appropriateness of long-term treatment for accident victims is delayed, cases of prolonged treatment that are difficult to filter out under the current system continue to rise. Critics point out that there is a lack of objective procedures to assess the necessity for additional treatment, leading to treatment durations extending from months to years and increasing the burden of auto insurance payouts.According to the insurance industry on July 13, data from four major property and casualty insurers revealed that from January 2023 to the first half of last year, 8,242 accident victims received medical certificates more than 18 times. In 2023, the first year that required additional medical certificates for treatment extending beyond four weeks, 140 accident victims received certificates 18 times or more. This number has significantly increased as cases of repeated certificate issuance to extend treatment have continued.The Board of Audit and Inspection also highlighted similar cases. A man diagnosed with a grade 12 spinal sprain following a January 2023 accident submitted 31 similar medical certificates to extend his treatment period, incurring medical expenses of 1,455,000 won.The insurance industry cites the absence of an objective review process for assessing the necessity of additional treatment as a key reason for the recurrence of long-term treatment. Currently, when a medical institution diagnoses the need for further treatment, insurers find it challenging to verify its appropriateness separately. The existing method, which only checks for the submission of medical certificates, has limitations in managing long-term treatment.The Ministry of Land, Infrastructure and Transport and financial authorities have been promoting the introduction of the '8-week rule,' which would allow a public body to assess the necessity for additional treatment for accident victims receiving care beyond eight weeks. The aim is to protect patients who genuinely need long-term treatment while filtering out cases where the necessity for treatment is unclear.However, the traditional medicine sector has pushed back, arguing that imposing a uniform limit on treatment duration does not reflect patients' conditions and recovery speeds. As disagreements persist, the implementation of the new system remains stalled.As long-term treatment continues, the financial burden of traditional medicine is also increasing. Last year, the average cost of traditional medicine per accident victim at four major property and casualty insurers was 1,083,000 won, nearly three times higher than the average cost of Western medicine, which was 355,000 won.There has also been a rise in what is known as 'set billing,' where patients receive six or more of eight traditional treatments, including acupuncture, moxibustion, cupping, and herbal injections, in a single visit. Last year, the total outpatient treatment costs for traditional medicine at the four major insurers amounted to 817.4 billion won, with set billing accounting for 64.4% of that total.The insurance industry views the expansion of set billing as one of the factors contributing to the increase in traditional medicine costs. However, the traditional medicine sector maintains that multiple treatments can be administered based on patient conditions and that it cannot be assumed that multiple procedures indicate over-treatment.An insurance industry representative stated, 'The current four-week payment guarantee process only verifies the submission of medical certificates and does not objectively assess the appropriateness of additional treatment. The core of the 8-week rule is to ensure that medical judgments are made by a public body.' He added, 'As long-term treatment continues in some medical institutions, effective management measures are necessary.'* This article has been translated by AI. 2026-07-13 17:12:00
-
KOSPI Falls Below 7000 Amid Semiconductor Stock Decline The KOSPI index has fallen below the 7000 mark for the first time in over two months. This decline comes despite the successful listing of SK Hynix's American Depositary Receipts (ADR) and strong semiconductor export performance. Concerns over a potential breakdown in U.S.-Iran peace talks have further dampened investor sentiment. Analysts predict that extreme market volatility will continue for the foreseeable future.On July 13, the Korea Exchange reported that the KOSPI closed at 6806.93, down 669.01 points (8.95%) from the previous trading day, marking the third-largest drop this year. Since January, there have been 11 trading days where the KOSPI fell more than 5%, six days with declines over 7%, and four days, including today, with drops exceeding 8%. Notably, in the past month alone, significant declines have occurred on June 8 (-8.29%), June 23 (-9.99%), and July 2 (-7.89%), raising concerns about ongoing market volatility.The semiconductor sector was at the center of today's decline, with heavy selling pressure on major stocks like Samsung Electronics and SK Hynix. SK Hynix plummeted 15.37% to close at 1,845,000 won, losing the 1,900,000 won mark, while Samsung Electronics fell 10.7% to finish at 254,500 won. Other semiconductor stocks, including SK Square (-17.60%) and Samsung Electro-Mechanics (-18.62%), also experienced double-digit losses.Despite the recent strong performance of SK Hynix's ADR on the Nasdaq and solid growth in semiconductor earnings, the market reacted more sensitively to concerns about a peak in memory chip demand.Additionally, rising geopolitical tensions in the Middle East due to U.S.-Iran conflicts have intensified risk-averse sentiment among investors. With international oil prices and the dollar strengthening, and U.S. stock index futures showing weakness, negative sentiment quickly spread to the domestic market.Supply and demand dynamics also contributed to the index's decline. While individual investors made net purchases of 3.88 trillion won in a bid to buy at lower prices, it was insufficient to support the market. Foreign investors sold a net 1.73 trillion won, and institutions sold a net 2.2 trillion won, leading the index lower. This month, pension funds engaged in rebalancing, recording a net sale of 646 billion won.Hwang Seung-taek, head of research at Hana Securities, stated, “Concerns about the peak in the memory semiconductor market and deteriorating investor sentiment are the main causes of the decline. The selling by foreign investors has exacerbated volatility, increasing fatigue and risk-averse sentiment among market participants.” 2026-07-13 17:12:00
-
Dongyang Life Insurance Hosts 2026 Leaders Forum to Discuss Growth Strategies in the AI Era Dongyang Life Insurance held a Leaders Forum aimed at enhancing employees' capabilities in artificial intelligence (AI) and business innovation, sharing its medium- to long-term growth strategies.The company announced on July 13 that it hosted the '2026 Second Half Leaders Change and Innovation Forum' on July 10 at its Talent Development Center, attended by executives, team leaders, and department heads.The forum was themed 'Redesigning Growth in the AI Era.' It aimed to share directions for transitioning to a medium- to long-term growth system in response to the rapidly changing financial and insurance industry environment and to discuss innovative business strategies utilizing AI.The event was divided into two parts, starting with a presentation on medium- to long-term growth strategies by the head of the Management Innovation Division, followed by a special lecture on AI from a global consulting firm and discussions on business innovation by sector.In the first part, representatives from the global management consulting firm Kearney delivered a lecture on 'AI Technology Development, Industry Changes, and Corporate AI Transformation (AX) Strategies.' Attendees examined the impact of AI on insurance product development, sales, asset management, and overall business processes, discussing organizational operational directions and the role of leaders in securing competitiveness.The second part shared AI utilization strategies across key business sectors, including sales, asset management, and management. The sales and product sectors proposed building a 'mega sales channel' and enhancing product competitiveness through customer analysis and improved sales productivity using AI and data.The investment, finance, and risk sectors discussed integrating AI into asset management decision-making and risk management to enhance operational competitiveness and establish a stable revenue base. In the management sector, which includes IT, operations, and consumer protection, strategies for utilizing AI to automate tasks and strengthen consumer protection and internal controls to ensure the reliability and stability of financial companies were also addressed.Dongyang Life Insurance CEO Seong Dae-kyu stated, "It is crucial to quickly develop solutions that fit our work internally. Let us establish a culture where all employees learn and utilize AI, enabling us to change and grow independently."* This article has been translated by AI. 2026-07-13 17:12:00
-
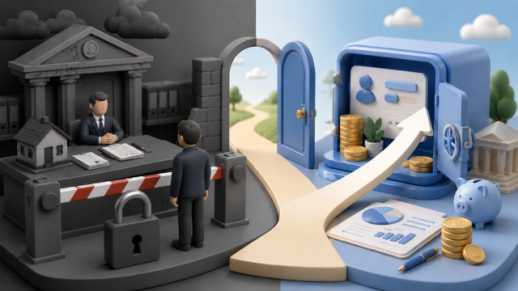 Gov't tightens household loans while mulling pension-backed borrowing options SEOUL, July 13 (AJP) - South Korea is tightening conventional household lending to contain debt growth while considering measures that could make it easier to borrow and invest against retirement savings, exposing a potential contradiction in its financial policy. One channel of household leverage is being restricted just as another could be opened. Household lending at the country's five largest banks - KB Kookmin, Shinhan, Hana, Woori and NH NongHyup - excluding government-backed loans rose by 3.697 trillion won (US$2.46 billion) to 647.578 trillion won at the end of June from 643.882 trillion won at the end of last year, according to banking industry data. The increase represented 85.3 percent of the lenders' combined annual household loan growth target of 4.336 trillion won, leaving them with limited room to expand credit in the second half. The targets are not statutory lending caps but management plans submitted by financial institutions in line with the government's household debt policy. Household lending across the financial sector increased by 29 trillion won in the first half, including 8.3 trillion won in June alone, according to the Financial Services Commission. Mortgage lending rose by 4.5 trillion won in June, while other borrowing, including unsecured credit, increased by 3.7 trillion won. The FSC has instructed financial institutions to review their second-half lending strategies and monthly and quarterly management plans, warning that home transactions and previously approved group loans could keep mortgage growth elevated. Banks have already begun raising borrowing barriers, with KB Kookmin Bank cutting the maximum amount available for home-purchase mortgages to 300 million won from 600 million won and some lenders restricting unsecured loans or reducing overdraft limits. The pullback is likely to weigh most heavily on households that need new credit, rather than existing assets, to enter the property or financial markets. At the same time, local media have reported that the government is considering measures to make retirement pension-backed loans commercially viable and gradually raise the risk-asset investment ceiling for defined contribution plans and individual retirement pension accounts from the current 70 percent. The Ministry of Employment and Labor has said, however, that neither pension-backed lending nor a phased increase in the risk-asset ceiling has been finalized. Current law generally prohibits the transfer, seizure or pledging of retirement pension benefits, while allowing them to be used as collateral in limited cases prescribed by presidential decree, including home purchases. Financial institutions have rarely offered such products because of strong legal protections for pension benefits and uncertainty over how collateral rights could be enforced in the event of default. Supporters argue that people facing urgent cash needs should be able to borrow against their retirement savings rather than permanently withdraw money from their accounts. The number of people making early withdrawals from retirement pension accounts rose 4.3 percent to 67,000 in 2024, while the amount withdrawn increased 12.1 percent to 2.7 trillion won, according to the National Data Agency. Home purchases accounted for 56.5 percent of withdrawals by number and rental housing deposits another 25.5 percent, putting the share of housing-related withdrawals above 80 percent. Replacing early withdrawals with secured loans could allow account holders to meet temporary funding needs while keeping their retirement assets invested. Outstanding retirement pension assets surpassed 500 trillion won for the first time at the end of last year, rising 16.8 percent to 501.4 trillion won, according to the Labor Ministry and the Financial Supervisory Service. Defined contribution plans and individual retirement pension accounts, in which participants make their own investment decisions, accounted for 54.3 percent of the total, while market-linked products represented 24.6 percent. If the proposed changes are introduced, people with sufficient pension balances could raise cash without withdrawing their savings or increase their exposure to equities and other risk assets. The opportunity, however, would not be equally available to all workers. As of June 2025, 61.7 percent of regular workers were enrolled in retirement pension plans, more than double the 29.8 percent rate among non-regular workers. People with stable employment and long contribution records would be better placed to use pension assets as collateral or investment capital, while workers outside the system or with small balances would have little to leverage. A retirement pension industry official who requested anonymity said the two policies should be viewed separately because "pension-backed loans are intended to preserve retirement assets by reducing early withdrawals," while conventional household lending controls are designed to curb excessive flows into property and equity markets and contain financial stability risks. The difference in their stated objectives, however, does not fully remove the tension between the two approaches. Replacing withdrawals with loans would not eliminate households’ funding shortages or debt-servicing burdens, while borrowers who fail to repay could ultimately damage their future retirement income. If pension-backed loans are used to finance property or financial asset purchases, leverage that the government is attempting to suppress through conventional lending channels could simply re-emerge through retirement accounts. The policy could therefore send a mixed signal by restricting borrowing against income and future earnings while making it easier to borrow against accumulated pension wealth. It could also reinforce disparities between people who need credit to acquire their first meaningful assets and those who already hold assets that can be pledged or invested. Regulators would need to determine whether pension-backed loans should count toward financial institutions’ household loan growth targets and borrowers' debt service ratios. Clear rules would also be required on eligible borrowing purposes, collateral limits and the protection of pension benefits in the event of default, while any increase in the risk-asset ceiling would need to account for differences in pension balances and investment capacity. Without such safeguards, the government could end up curbing one form of household leverage while encouraging another, shifting debt rather than reducing it and allowing existing wealth to determine access to the next round of financial opportunity. 2026-07-13 17:08:40
-
Controversy Surrounds Single-Stock Leverage as Blue House Steps In The controversy over single-stock leverage is escalating. As it becomes a point of contention between political parties, the Blue House has intervened. Kim Yong-beom, head of the Blue House Policy Office, stated on July 10, "If it is determined that improvements to the single-stock leverage system are necessary, decisions will be made at the market situation inspection meeting (F4) involving the Ministry of Finance, the Financial Services Commission, the Bank of Korea, and the Financial Supervisory Service." While the debate intensifies, solutions vary among stakeholders.As of July 13, the Financial Services Commission is reviewing improvement measures for single-stock leverage products in collaboration with relevant agencies, including the Financial Supervisory Service, the Korea Exchange, and the Korea Financial Investment Association. On July 14, the commission plans to discuss market response strategies with representatives from major securities firms and asset management companies.However, there are subtle differences in positions among the agencies. The Financial Services Commission, the primary regulatory body, is cautious about viewing single-stock leverage as a direct cause of recent market volatility. There is a prevailing sentiment against the possibility of delisting or halting the launch of new products, as doing so could lead to realized investor losses and undermine policy credibility. Nonetheless, there is consensus on the need to enhance investor protection, prompting a comprehensive review of entry requirements.In contrast, the Financial Supervisory Service advocates for stricter regulations. The controversy was further fueled by Lee Chan-jin, the head of the Financial Supervisory Service, who criticized the launch of these products during a press conference on June 22, stating, "We should have prevented their release at all costs." However, the Financial Supervisory Service has not publicly clarified what additional regulatory measures should be implemented.The final decision is expected to be made following the Financial Services Commission's presidential briefing on July 15 and subsequent F4 meetings. The market anticipates that the measures will focus on strengthening entry barriers. Proposed solutions include increasing the minimum deposit requirement and enhancing investor education. Currently, to invest in single-stock leverage products, investors must deposit a minimum of 10 million won and complete one hour each of general and advanced training through the Financial Investment Association's learning system. The association is reportedly considering a comprehensive overhaul of the training content.* This article has been translated by AI. 2026-07-13 17:08:00
-
KOSPI Plummets Nearly 9% Amid Panic, Driven by Four Key Triggers The South Korean stock market experienced another 'Black Monday' as the KOSPI index fell nearly 9%, dropping below the 7000 mark for the first time in over two months. The KOSDAQ also fell below 800. Analysts attribute the market crash to a combination of weakened investor sentiment centered around semiconductors and deteriorating supply-demand conditions.On July 13, prior to the market opening, there was optimism regarding a potential rise in the stock market due to the listing of SK Hynix's American Depositary Receipts (ADRs), driven by expectations of a so-called 'reverse kimchi premium.' On its first day of trading on the Nasdaq, SK Hynix saw a double-digit increase, indicating strong interest from global investors. However, the reality was starkly different, as SK Hynix's stock price plummeted by 15.37% by the end of the trading day. Analysts suggested that this decline was due to the exhaustion of positive sentiment surrounding the ADR listing, as much of the anticipated gains had already been factored into the stock price, leading to a wave of profit-taking.Concerns about a potential peak in the semiconductor sector also contributed to the decline in investor sentiment. The semiconductor industry now accounts for over 60% of the KOSPI's market capitalization, and as the sector faltered, the overall index suffered. Korea Investment & Securities projected that SK Hynix's second-quarter operating profit would fall short of market expectations, citing lower-than-expected average selling price increases and the anticipated impact of next-generation HBM4 production starting in the third quarter. Some investors interpreted this as a sign of slowing growth in AI memory, further fueling peak concerns.Another factor exacerbating the market decline was the resurgence of 'Middle East risk.' Over the weekend, tensions escalated between the U.S. and Iran over the Strait of Hormuz, leading to a rapid spread of risk-averse sentiment. According to Bloomberg, Brent crude futures for September rose by 4.26% to $79.25 per barrel, while West Texas Intermediate (WTI) futures for August increased by 4.34% to $74.51 per barrel. However, analysts believe the impact of this factor was limited. Han Ji-young, a researcher at Kiwoom Securities, noted that despite the initial excitement surrounding SK Hynix's ADR listing, concerns about a peak in the memory market persisted, causing increased volatility in semiconductor stocks and heightened sensitivity to negative news and reports.Lastly, a supply-demand cycle, referred to as the 'Wag the Dog' phenomenon, amplified the market's decline. Market participants observed that derivatives and supply-demand factors, such as futures, leveraged ETFs, and margin trading, increased volatility in the spot market, further deepening the losses. As semiconductor stocks fell, investor sentiment weakened, leading to liquidations of leveraged ETFs and forced selling, which in turn triggered program selling and foreign futures selling, creating a vicious cycle that exacerbated the index's decline. Lee Kyung-min, a researcher at Daishin Securities, stated that the recent drop in semiconductor stocks resulted from a combination of narratives surrounding the AI industry, valuation corrections, and leveraged liquidations, leading to a more significant decline in the domestic market compared to global markets. Kim Seok-hwan, a researcher at Mirae Asset Securities, added that the sharp drop in SK Hynix's stock was more a result of the conclusion of the ADR listing event and profit expectations being priced in, rather than a direct reflection of a slowdown in the semiconductor market or profit outlook, emphasizing the need to monitor the preliminary second-quarter results scheduled for July 29 and guidance on capital expenditures from AI hyperscalers.* This article has been translated by AI. 2026-07-13 17:08:00
-
KOSPI Falls Below 7000, Analysts Say It's Not a Bear Market Yet The KOSPI index has fallen below 7000 for the first time in over two months, but analysts from various securities firms assert that this does not indicate a transition to a bear market. They believe the recent drop is more a result of short-term supply and demand shocks rather than a decline in corporate earnings. While the market has entered an oversold phase, analysts maintain that the long-term upward trend remains intact.In a weekly report on July 13, global investment bank Goldman Sachs noted that the KOSPI's 12-month forward price-to-earnings ratio (PER) has dropped to 6.2, the lowest level since 2004. They described this as an attractive risk-reward scenario from a valuation perspective. Morgan Stanley also pointed out that over 70% of KOSPI-listed companies are trading below a price-to-book ratio (PBR) of 1, maintaining a target of 12,000 for the KOSPI.Domestic securities firms attribute the recent decline more to investor sentiment and supply and demand factors than to corporate performance. Kim Do-eon, a researcher at Hana Securities, stated, "The current adjustment is more akin to a rebalancing process following an initial rise, rather than the start of a bear market. Foreign selling, the National Pension Service's rebalancing, and a slowdown in individual liquidity are delaying the index's recovery, but the direction of semiconductor profits has not yet turned negative." He added, "The current market issue is supply and demand rather than earnings," suggesting that this adjustment could be a preparatory phase for a second upward movement.However, there are concerns about further volatility. Kang Jin-hyuk, a senior researcher at Shinhan Investment Corp., noted, "The KOSPI is approaching the 50% retracement level of its gains since the end of March," and warned that the potential for an undershooting due to supply and demand dynamics remains. Conversely, Daishin Securities stated, "There is no disruption in fundamentals such as earnings and economic outlook," predicting that the KOSPI's 12-month forward PER has entered a historically undervalued range, which should support the market as the second-quarter earnings season begins.Hwang Seung-taek, head of research at Hana Securities, explained that the recent adjustment is primarily due to concerns about the memory semiconductor market and deteriorating investor sentiment. He noted that foreign selling and other supply issues have increased volatility, leading to heightened fatigue and risk-averse sentiment among market participants.* This article has been translated by AI. 2026-07-13 17:08:00
-
Investors Buy the Dip Amid Market Volatility, Individual Investors Net 13 Trillion Won Despite recent fluctuations in the KOSPI, individual investors have actively engaged in buying on dips rather than exiting the market. While foreign investors took significant profits, individuals recorded net purchases exceeding 13 trillion won, primarily focusing on large-cap semiconductor stocks.According to the Korea Exchange, individual investors net bought 13.2416 trillion won in the securities market from July 1 to July 13. In contrast, foreign investors net sold 14.1051 trillion won, while institutions net bought 3.506 trillion won.The buying trend among individuals was concentrated in large-cap semiconductor stocks. The top net purchases during this period included SK Hynix and Samsung Electronics, followed by Samsung Electro-Mechanics, Hanwha Ocean, LS ELECTRIC, and LG Energy Solution. This trend is interpreted as a response to the recent price adjustments that eased the burden on semiconductor and large tech stocks.However, overall investment liquidity in the stock market has slightly decreased. Investors are withdrawing funds amid extreme market volatility. According to the Korea Financial Investment Association, as of July 10, the total investor deposit was 105.5758 trillion won, a decrease of 1.5521 trillion won from the previous trading day.Market analysts have noted that the recent sharp decline in the domestic stock market is more influenced by investor sentiment and supply-demand issues than by deteriorating corporate earnings. Lee Jun-young, a researcher at Eugene Investment & Securities, stated, "The recent drop in semiconductors is a result of supply-demand dynamics and volatility rather than earnings deterioration. Therefore, it is essential to maintain a buying perspective as this decline does not harm the overall profitability of the semiconductor sector."Lee Kyung-min, a researcher at Daishin Securities, added, "The recent semiconductor drop is a complex result of cracks in the AI industry's narrative, valuation corrections, and supply shocks due to leverage liquidation. The upcoming second-quarter earnings season and the results announcements from major tech companies like Samsung Electronics and SK Hynix at the end of July will be pivotal for restoring investor sentiment."* This article has been translated by AI. 2026-07-13 17:04:00
-
Rising Treatment Costs for Long-Term Auto Insurance Patients Treatment costs for auto insurance patients with minor injuries are increasingly concentrated among those requiring long-term care. Although only 1 in 10 patients receiving traditional medicine exceeded 8 weeks of treatment, they accounted for more than half of the total treatment costs.According to the insurance industry on July 13, an analysis of auto insurance claims from major insurers, including Samsung Fire & Marine Insurance, DB Insurance, Hyundai Marine & Fire Insurance, and KB Insurance, revealed that there were 1,226,000 patients with minor injuries, such as neck and back strains, classified as level 12-14. Of these, 1,085,000 patients (88.5%) completed their treatment within 8 weeks. The number of patients who received treatment beyond 8 weeks was 141,000, representing 11.5% of the total.The share of treatment costs for long-term patients was significantly higher than their share of the total patient population. Out of a total treatment cost of 998.65 billion won for minor injury patients, 369.03 billion won was paid to those treated for more than 8 weeks, accounting for 37.0%. While these patients made up only 1 in 10, they received more than one-third of the total treatment costs.The 8-week mark is often cited as a threshold for determining long-term treatment in auto insurance cases. The government and financial authorities are working on measures to objectively assess the necessity of treatment for patients who exceed the typical treatment period for conditions like strains. The aim is to protect patients who genuinely need long-term care while reducing unnecessary insurance payouts.This concentration of treatment costs is particularly pronounced in traditional medicine. Among the 604,000 patients who received only traditional treatment, 58,000 (9.7%) exceeded 8 weeks of care. However, they received 115.84 billion won, which is 53.0% of the total traditional treatment costs of 218.62 billion won.In contrast, patients who received only Western medicine showed a stark difference. Of the 322,000 patients treated solely with Western medicine, 14,000 (4.3%) exceeded 8 weeks. They received 16.76 billion won, which is only 7.9% of the total Western treatment costs. The share of treatment costs for those exceeding 8 weeks in traditional medicine was 45.1 percentage points higher than that for Western medicine.Patients receiving both traditional and Western treatments also had a high proportion of long-term care. Among 300,000 patients who received combined treatment, 69,000 (23.0%) were treated for more than 8 weeks. They accounted for 2.36 trillion won, or 41.7% of the total costs for combined treatment.The increase in long-term treatment costs is also impacting the loss ratio for auto insurance. As of May this year, the cumulative loss ratio for the four major insurers was 84.7%, up 1.9 percentage points from the same period last year.Auto insurance operates on a structure where payouts to some policyholders are shared among all policyholders through premiums. Last year, about 85% of auto insurance policyholders were accident-free drivers. The insurance industry warns that if the appropriateness of treatment after 8 weeks is not properly managed, it could lead to increased premium burdens for the majority of drivers.An industry official stated, “Expectations that measures for managing long-term treatment beyond 8 weeks will be implemented have been reflected in this year’s auto insurance premium increase calculations, which has limited the extent of the increase. However, if the introduction of these measures is delayed and coincides with an increase in accidents during the rainy season, the burden of auto insurance losses could grow.”* This article has been translated by AI. 2026-07-13 17:04:00
-
Discounts of up to 800 won for using personal cups as government and cafes join forces to reduce plastic Starting in September, customers using personal cups at over 22,000 locations nationwide, including Starbucks, Ediya, and McDonald's, will receive discounts and carbon-neutral points totaling up to 800 won. This initiative is part of the government's effort to reduce single-use cups in collaboration with the cafe and fast-food industries.The Ministry of Climate, Energy, and Environment announced on July 13 that it has signed a 'Plastic Reduction Culture Promotion Agreement' with 23 brands from the coffee, fast food, and bakery sectors at the Seoul Reuse Plaza. Participating brands include Starbucks, Twosome Place, Ediya, McDonald's, Lotteria, and Paris Baguette, among others, covering more than 22,000 stores nationwide.This agreement follows the government's 'Plastic Circular Economy Promotion Plan' announced in April, aimed at reducing plastic use in everyday spaces like cafes and promoting a circular economy culture.The core of the agreement is to decrease the use of single-use cups in stores and increase the use of reusable cups. Participating companies will expand the use of reusable cups in their stores and offer discounts and carbon-neutral points to customers who bring their own cups. When combining store-specific discounts and carbon-neutral points, consumers can receive benefits of up to 800 won.Participating stores will provide straws only upon separate request at kiosks or from staff and will work to reduce the use of hard-to-recycle plastic and metal composite containers. The practice of serving drinks in two stacked single-use cups will also be addressed.Stores will display 'Personal Cup Discount Store' signage to help consumers easily identify participating locations. The Ministry of Climate plans to implement detailed action plans starting in September and analyze the results of the agreement to inform future policies on reducing single-use items.Minister of Climate, Energy, and Environment Kim Seong-hwan stated, "The transition to a plastic-free society begins in everyday spaces like cafes. We will expand this culture of practice to funeral homes, businesses, amusement parks, and sports venues."* This article has been translated by AI. 2026-07-13 17:04:00