
The United States is accelerating its efforts to dominate the digital currency market through a "stablecoin race." A legal framework has been established allowing private entities to issue digital currencies pegged to the dollar, backed 1:1 by safe assets such as cash and short-term government bonds. The "Clarity for Payment Stablecoins Act," which has passed the House Financial Services Committee, marks the first federal legal benchmark for the issuance, backing assets, and oversight of stablecoins. Market analysts predict that the dollar stablecoin market could grow to $1 trillion by around 2027. This initiative goes beyond mere cryptocurrency regulation; it aims to institutionalize dollar dominance in the digital age.
Stablecoins are not speculative assets like Bitcoin that experience extreme price fluctuations. Instead, they are digital payment methods closely tied to the value of fiat currencies like the dollar or won, used for payments, remittances, and settlements. This could lead to faster international money transfers and significantly lower transaction costs for businesses. Just as the internet and mobile technology have replaced traditional bank branches, blockchain-based payment networks have the potential to transform existing financial infrastructures. The U.S. is pushing forward in this market, believing that as stablecoins grow, the demand for U.S. Treasury bonds will increase, thereby expanding the use of the dollar in digital spaces.
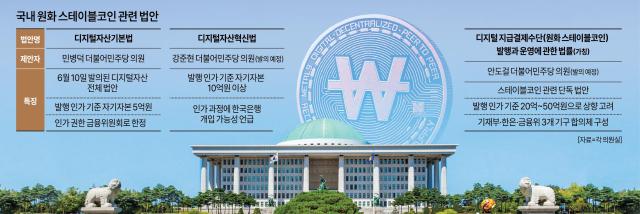
In contrast, South Korea's response remains cautious, hindered by differing opinions among government agencies. Discussions are ongoing about whether to allow won stablecoins exclusively through banks or to open the market to fintech and big tech companies, as well as how to incorporate concerns about monetary policy and financial stability from the Bank of Korea. The central bank maintains that if a won stablecoin is introduced, it should start with strictly regulated institutions like banks. Financial authorities have also considered a bank consortium approach, but perspectives in the National Assembly and the industry continue to diverge.
While the U.S. acknowledges the risks and chooses to integrate them into a regulatory framework, South Korea is delaying discussions due to these very risks. Meanwhile, domestic users are already utilizing dollar stablecoins in their daily transactions. Without a regulated alternative in won, the market is likely to gravitate towards dollar-based services. This issue extends beyond the competition in the cryptocurrency industry; it poses a national risk regarding the diminishing presence of the won in digital payment networks.
South Korea must pursue two simultaneous strategies. First, it needs robust safety measures: 100% backing of reserve assets, separation of customer assets, continuous disclosures, external audits, immediate redemption obligations, and anti-money laundering standards should be fundamental. Legal provisions must ensure that user assets are fully protected even if the issuer goes bankrupt. Second, it should allow controlled experimentation. The Bank of Korea's ongoing tests for Central Bank Digital Currency (CBDC) should be linked to trials starting with banks, while gradually opening pathways for qualified fintech and payment service providers. Limiting participation to banks may enhance stability but could slow innovation. Conversely, unrestricted access could undermine trust. The solution lies not in prohibition but in strict licensing and differentiated regulations.
The won stablecoin could become a foundational infrastructure for South Korea's financial future, or it could devolve into a secondary market for dollar stablecoins if neglected. What is needed now is neither vague optimism nor excessive fear. If South Korea continues to engage in repetitive discussions while the U.S. moves forward with both legal and market initiatives, the competition may already be lost. We are at a pivotal moment in the reorganization of digital financial order. To maintain the won's presence in the digital payment landscape, both the government's regulatory pace and the industry's innovation speed must significantly accelerate.
Stablecoins are not speculative assets like Bitcoin that experience extreme price fluctuations. Instead, they are digital payment methods closely tied to the value of fiat currencies like the dollar or won, used for payments, remittances, and settlements. This could lead to faster international money transfers and significantly lower transaction costs for businesses. Just as the internet and mobile technology have replaced traditional bank branches, blockchain-based payment networks have the potential to transform existing financial infrastructures. The U.S. is pushing forward in this market, believing that as stablecoins grow, the demand for U.S. Treasury bonds will increase, thereby expanding the use of the dollar in digital spaces.
In contrast, South Korea's response remains cautious, hindered by differing opinions among government agencies. Discussions are ongoing about whether to allow won stablecoins exclusively through banks or to open the market to fintech and big tech companies, as well as how to incorporate concerns about monetary policy and financial stability from the Bank of Korea. The central bank maintains that if a won stablecoin is introduced, it should start with strictly regulated institutions like banks. Financial authorities have also considered a bank consortium approach, but perspectives in the National Assembly and the industry continue to diverge.
While the U.S. acknowledges the risks and chooses to integrate them into a regulatory framework, South Korea is delaying discussions due to these very risks. Meanwhile, domestic users are already utilizing dollar stablecoins in their daily transactions. Without a regulated alternative in won, the market is likely to gravitate towards dollar-based services. This issue extends beyond the competition in the cryptocurrency industry; it poses a national risk regarding the diminishing presence of the won in digital payment networks.
South Korea must pursue two simultaneous strategies. First, it needs robust safety measures: 100% backing of reserve assets, separation of customer assets, continuous disclosures, external audits, immediate redemption obligations, and anti-money laundering standards should be fundamental. Legal provisions must ensure that user assets are fully protected even if the issuer goes bankrupt. Second, it should allow controlled experimentation. The Bank of Korea's ongoing tests for Central Bank Digital Currency (CBDC) should be linked to trials starting with banks, while gradually opening pathways for qualified fintech and payment service providers. Limiting participation to banks may enhance stability but could slow innovation. Conversely, unrestricted access could undermine trust. The solution lies not in prohibition but in strict licensing and differentiated regulations.
The won stablecoin could become a foundational infrastructure for South Korea's financial future, or it could devolve into a secondary market for dollar stablecoins if neglected. What is needed now is neither vague optimism nor excessive fear. If South Korea continues to engage in repetitive discussions while the U.S. moves forward with both legal and market initiatives, the competition may already be lost. We are at a pivotal moment in the reorganization of digital financial order. To maintain the won's presence in the digital payment landscape, both the government's regulatory pace and the industry's innovation speed must significantly accelerate.
* This article has been translated by AI.
Copyright ⓒ Aju Press All rights reserved.